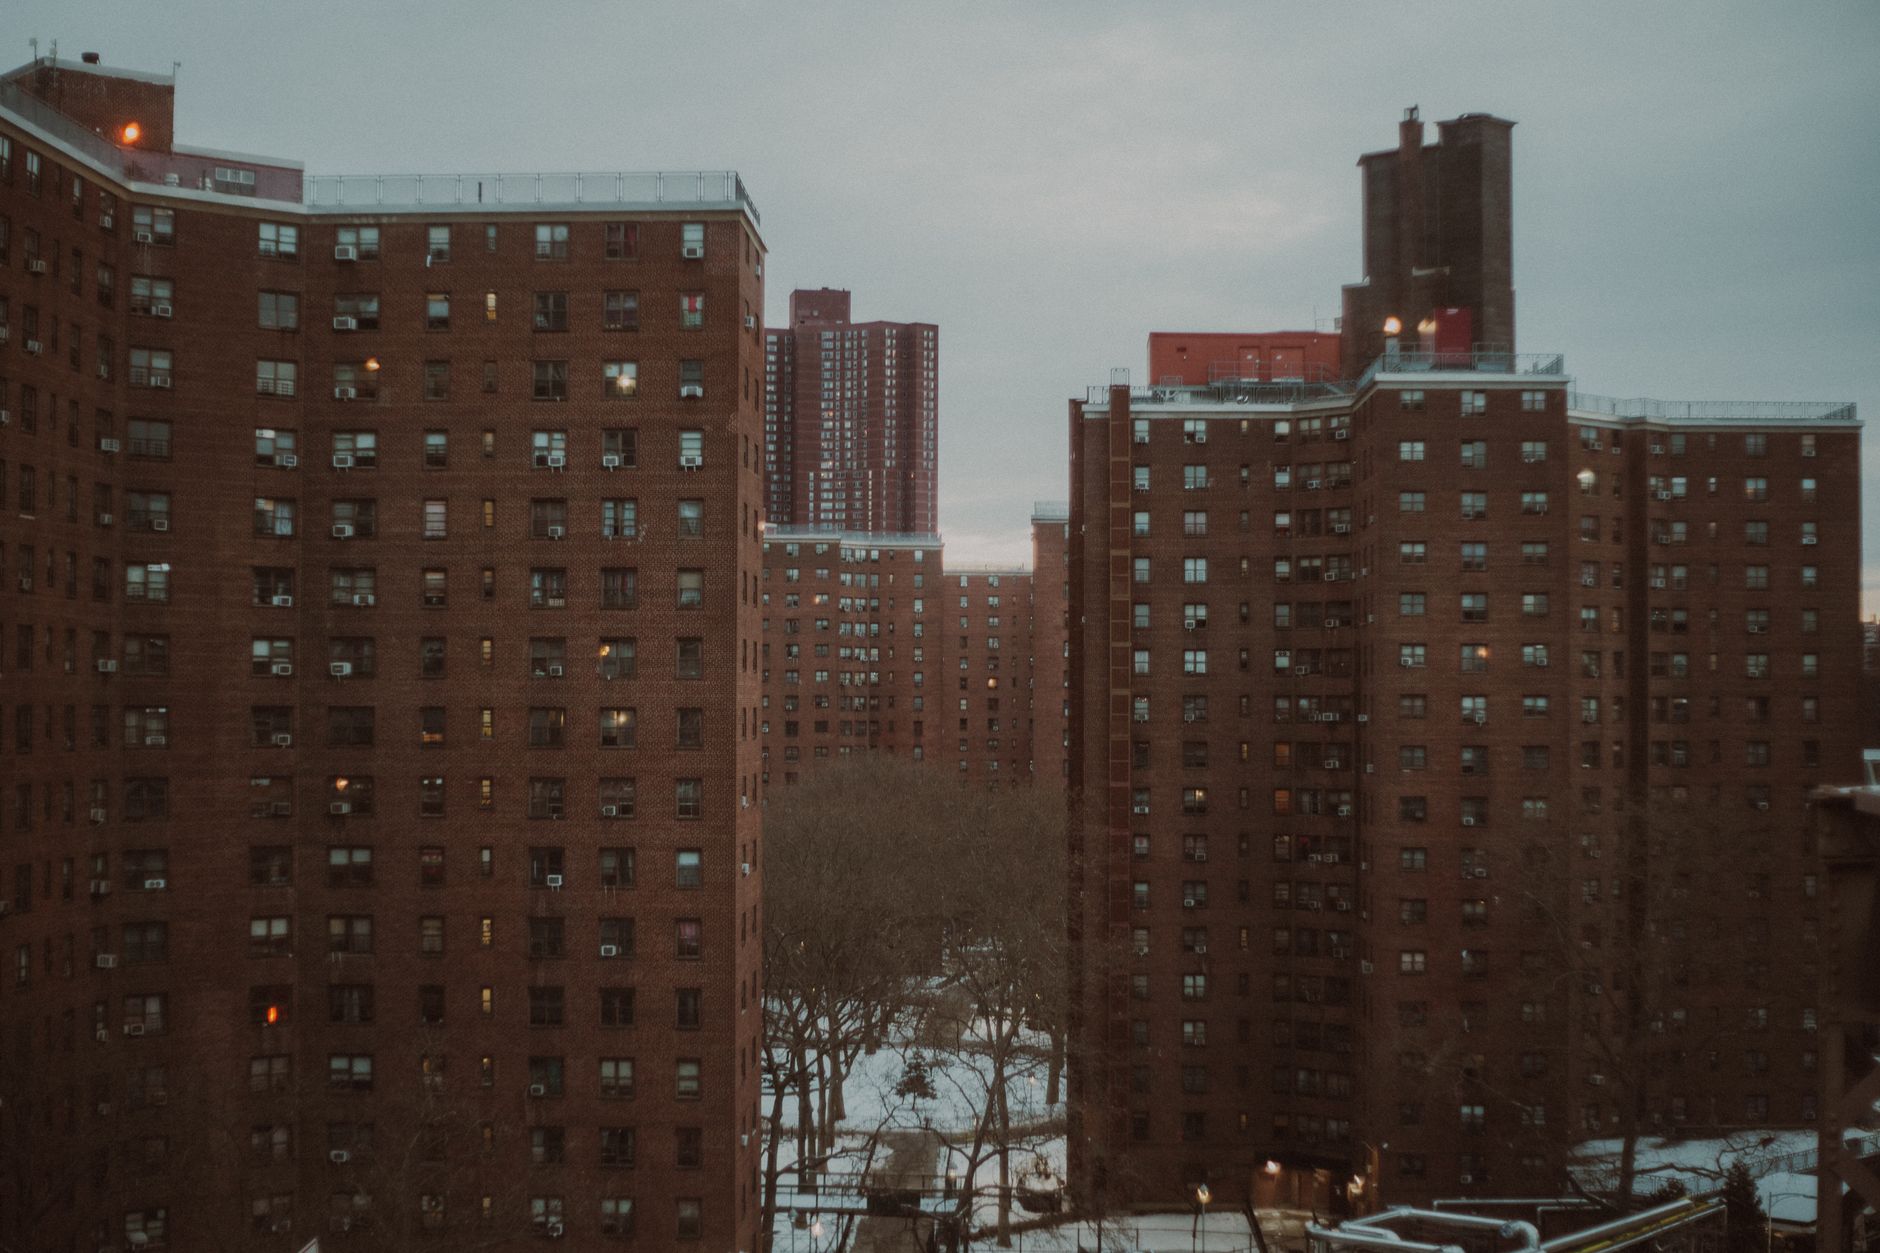
Brooklyn Multifamily Cap Rates by Submarket
Submarket location is the single most powerful predictor of where a Brooklyn multifamily asset prices. Institutional-grade neighborhoods with strong transit access, high household incomes, and Manhattan adjacency command the tightest yields. Outer corridors with longer rent-growth runways and higher vacancy risk price wider. These demand fundamentals help explain why free-market assets trade at cap rates nearly 100 basis points lower than comparable rent-stabilized buildings, a spread documented in Brooklyn H1 2025 market data. Cap rates reflect both income yield and liquidity premium. Where institutions compete, spreads compress.
North Brooklyn: Williamsburg, Greenpoint, and DUMBO
North Brooklyn represents the most liquid and institutionally active multifamily submarket in the outer boroughs. The depth of buyer demand in North Brooklyn is what separates it from every other outer-borough submarket.
Central Brooklyn: Park Slope, Crown Heights, and Prospect Heights
Central Brooklyn spans a meaningful range of investor profiles and risk tolerances, from the conservative owner-user demand in Park Slope to the more yield-oriented value-add buyers active in Crown Heights. Free-market Crown Heights walk-ups price tighter, reflecting the specific supply constraint on non-regulated units in this corridor. The Atlantic Avenue mixed-use corridor blurs the line between retail and residential cap rate benchmarks, introducing additional pricing variability that requires careful underwriting of ground-floor income stability.
Emerging Submarkets: Bushwick, East New York, and Flatbush
Bushwick presents one of the most nuanced underwriting challenges in Brooklyn multifamily. As of October 17, 2024, IAI rent increases for rent-stabilized apartments are governed by a two-tier system enacted in the NYS FY2024–2025 budget: Tier 1 allows recovery of up to $30,000 in costs over 15 years (up from HSTPA's $15,000), and Tier 2 allows up to $50,000 for qualifying vacant units, with both tiers now yielding permanent rent increases — significantly expanding the value-add potential compared to the original HSTPA framework. Flatbush delivers attractive gross rent multiples relative to other NYC boroughs. The risk premium embedded in these outer submarkets is real and rational, not simply an artifact of buyer hesitation.
Factors Driving Brooklyn Cap Rate Trends in 2026
Brooklyn cap rates have moved up from their 2021-2022 lows, reflecting a market that has been repricing for higher financing costs and more selective buyer underwriting. This decompression from prior-cycle lows is not evidence of market distress. It is a rational recalibration to a higher-rate financing environment. At Penn Plaza Property, we consistently see buyers in this environment anchoring underwriting to in-place NOI rather than pro-forma rent projections, particularly in submarkets with stabilization exposure.
How Rent Regulation Status Affects Brooklyn Cap Rate Pricing
The pricing bifurcation between free-market and rent-stabilized Brooklyn multifamily is one of the defining structural features of the current investment market. This spread is not arbitrary. The math is brutal.
Why Foreign Capital Keeps Brooklyn Multifamily Pricing Elevated
These investors view New York City as a safe-haven, dollar-denominated market with superior long-term liquidity relative to secondary U.S. cities or domestic Korean real estate. FIRPTA withholding rules apply to foreign investors in NYC commercial real estate transactions; a domestically-controlled REIT structure (where less than 50% of the REIT is held by foreign persons) can exempt foreign investors from FIRPTA on disposition of REIT shares, but LP structures do not provide a FIRPTA exemption — they subject foreign partners to partnership-level withholding on effectively connected income instead. The practical effect is that foreign capital provides a meaningful bid floor in competitive North and Central Brooklyn submarkets, dampening cap rate expansion even during periods when domestic buyers pull back on interest rate concerns. Our team at Penn Plaza Property works specifically with Korean investors navigating entity structuring, 1031 exchange compatibility, and off-market deal access in Brooklyn and Queens.
Brooklyn vs. Manhattan and Queens Multifamily Cap Rates
Understanding how Brooklyn prices relative to Manhattan and Queens is essential context for any NYC multifamily investor. Brooklyn offers a meaningful yield premium over Manhattan, making it the preferred outer-borough destination for investors who need better debt coverage ratios without sacrificing asset quality or liquidity. The spread between Brooklyn's borough-wide average and the broader New York multifamily market reflects a yield premium that compensates investors for underwriting uncertainty and asset-specific risk, particularly in stabilized-heavy portfolios.
| Submarket | Avg.
Brooklyn vs. Manhattan: Where Is the Risk-Adjusted Return Stronger?
Brooklyn offers a meaningful yield premium over comparable Manhattan assets, and in many cases the premium is wider when comparing Central or South Brooklyn to Manhattan core. That spread is real return. Debt coverage ratios are more achievable in Brooklyn at current interest rates given the wider starting cap rates, which is why sophisticated institutional investors increasingly treat North Brooklyn as functionally equivalent to Manhattan for portfolio allocation purposes.
Value-Add vs. Stabilized Multifamily: Cap Rate Strategy Across Brooklyn
The choice between stabilized and value-add Brooklyn multifamily is not simply a yield question. It is a fundamental decision about execution risk, financing structure, hold period, and regulatory exposure. The difference is execution certainty.
Which Brooklyn Submarkets Offer the Best Value-Add Cap Rate Upside?
Crown Heights and Prospect Lefferts Gardens offer the clearest rent-to-market upside in 2026. Many buildings in these corridors carry legacy tenants at below-market rents in nominally free-market units, creating genuine lease-up yield improvement potential without the HSTPA constraints that plague stabilized portfolios. Bushwick value-add deals require careful due diligence on stabilization exposure. The post-HSTPA IAI rent increase caps are modest, and buyers who underwrite aggressive stabilized yields in heavily regulated Bushwick buildings face real stranded-capital risk if the business plan stalls. East New York rezoning corridors offer the widest cap rate spreads in Brooklyn, but these require longer hold periods, stronger operational platforms, and deeper construction expertise than most private buyers maintain.
How Debt Markets Affect Cap Rate Underwriting for Brooklyn Acquisitions
Debt structure is the factor most often underweighted by first-time Brooklyn multifamily buyers. Bridge loan strategies for value-add deals in Manhattan submarkets such as Washington Heights, East Harlem, and Inwood typically target 18-36 month business plans designed to reach stabilized yields that clear positive leverage thresholds. Agency lender DSCR requirements directly constrain bid pricing in rent-stabilized-heavy Manhattan multifamily portfolios, because the in-place NOI cannot support the debt load at market purchase prices. This is where off-market deal flow creates genuine pricing advantages. Buyers who access assets before they reach the brokered market often secure a meaningfully tighter basis in effective cap rate terms than buyers competing in formal auction processes.
Brooklyn Multifamily Investment Outlook for 2026 and Beyond
Most active Brooklyn multifamily market participants expect cap rates to remain broadly range-bound through 2026, with submarket-level dispersion widening rather than tightening. Brooklyn performs better than the national average given its supply constraints and demand fundamentals.
How Interest Rate Movements Will Reshape Brooklyn Cap Rates Through 2027
According to CBRE Econometric Advisors research, multifamily cap rates have historically moved approximately 75 basis points for every 100 basis point change in the 10-year Treasury yield — meaning the relationship runs through Treasury rates rather than the Federal Funds Rate directly, and the precise compression in any given market will vary. The flip side is also real. Floating-rate borrowers on legacy bridge debt originated in 2021-2022 face refinancing pressure that may generate motivated sale opportunities in isolated Manhattan submarkets, creating cap rate-widening dynamics at the asset level even as the broader market holds. NYC Local Law 97 carbon emission compliance costs are beginning to factor into NOI projections for larger Class B and C multifamily buildings, adding a modest but real drag on effective cap rates for older assets requiring capital upgrades. New multifamily supply remains constrained by construction costs and zoning complexity across Brooklyn, which reinforces rent growth assumptions and limits the vacancy risk that would otherwise force buyers to demand wider yields.
Frequently Asked Questions
What is the average cap rate for multifamily properties in Brooklyn in 2026?
Which Brooklyn neighborhood has the lowest multifamily cap rates?
How do rent-stabilized buildings affect cap rate calculations in Brooklyn?
Is Brooklyn multifamily still a good investment at 2026 cap rates?
What is the cap rate spread between Brooklyn and Manhattan multifamily?
How does Local Law 97 affect multifamily cap rates and valuations in Brooklyn?
What cap rate should foreign investors target when buying Brooklyn multifamily?
How do interest rates impact Brooklyn multifamily cap rate trends in 2026?
What is the difference between going-in and stabilized cap rates for value-add Brooklyn deals?
What are current cap rates by Brooklyn submarket in 2026?
How do Brooklyn cap rates compare to Manhattan in 2026?
What trends are driving Brooklyn multifamily pricing now?
Are cap rates rising or falling in Downtown Brooklyn?
Sources & References
- MMCG Invest: Mid-2025 New York Multifamily Market Report (opens in a new tab)[industry]
- Matthews Real Estate Investment Services: Top 10 Multifamily Markets in 2026 (opens in a new tab)[industry]
- Ariel Property Advisors: NYC 2025 Multifamily Numbers (opens in a new tab)[industry]
- Mendy Realty: Brooklyn Multifamily Market Update (opens in a new tab)[industry]
- NYC Rules: Proposed Rent Guidelines October 2025 through September 2026 (opens in a new tab)[gov]
- Ronit Abraham: Multi-Family Investing in Crown Heights Brooklyn (opens in a new tab)[industry]
- SVN Miller Commercial Real Estate: Economic Update March 2026 (opens in a new tab)[industry]
- Changes to NYS Housing Laws Enacted in the FY24 Budget | Homes and Community Renewal (DHCR) (opens in a new tab)[factcheck]
- LL97 Greenhouse Gas Emissions Reduction - Buildings | NYC Department of Buildings (opens in a new tab)[factcheck]
- Definitions of terms and procedures unique to FIRPTA | Internal Revenue Service (opens in a new tab)[factcheck]
About the Author
Penn Plaza Property
Penn Plaza Property is a New York City real estate advisory firm specializing in commercial leasing, investment sales, and asset positioning for private investors, institutional capital, and Korean foreign investors across Manhattan, Brooklyn, and Queens.
Learn more at pennplazaproperty.com → (opens in a new tab)Related Posts
Where Should a Korean Investor Park $10M in NYC Real Estate Right Now?
Korean investors with $10M to deploy in NYC real estate face a bifurcated market with clear opportunity if you know where to look. This guide breaks down the four strongest asset classes by submarket, cap rate, and risk profile, with cross-border tax structuring considerations built in.
10 min read
What Is Last-Mile Industrial Real Estate and Why Are NYC Investors Paying a Premium?
Last-mile industrial real estate refers to small-to-mid-size warehouse and logistics facilities located close to dense urban consumers, designed to enable same-day and next-day delivery. In New York City, chronic land scarcity and surging e-commerce demand have pushed Brooklyn and Queens industrial rents to historic highs. This post defines the asset class and explains the structural forces driving NYC's premium valuations.
6 min read
How Does a Korean Investor Repatriate Profits from a U.S. Real Estate Sale?
Repatriating profits from a U.S. real estate sale involves clearing FIRPTA withholding, filing a U.S. tax return, and wiring net proceeds through a compliant bank channel. This guide walks Korean investors through each step, from closing-day obligations to final fund transfer to Korea.
10 min read